
I wasted my first five years of earning trying to budget the wrong way. I tracked every latte. I felt guilty about every dinner out. And my net worth barely moved. Then I learned how to budget for wealth building, and everything changed.
The problem was not that I spent too much on coffee. The problem was that I treated my budget like a diet instead of a plan. A wealth building budget is not about restriction. It is about direction. It tells your money where to go before someone else takes it.
This guide walks you through the framework I wish someone had given me. We will cover why normal budgets fail, the reverse-budget method, sample allocations at three income levels, how to automate it all, mistakes to avoid, and the tools that actually help. If you want to become rich, you need a plan. This is that plan.
Why Most Budgets Fail Wealth Builders
Most budgets are built for people who want to control spending. They are not built for people who want to build wealth. That is the first problem.
When you track every penny and try to cut every small joy, you burn out. I know I did. I spent three months logging every purchase. By month four, I quit. The budget was too tight and too focused on what I could not do.
Here are the real reasons budgets fail for wealth builders.
- They focus on cutting, not building. You can only cut so much. You cannot cut your way to a million dollars. You have to build income and assets too.
- They do not prioritize saving and investing. Most budgets treat savings as what is left over. But there is never anything left over. Savings must come first.
- They ignore income growth. A budget for a $50,000 salary looks nothing like a budget for a $150,000 salary. If you do not plan for raises and new income, your budget breaks.
- They are too complicated. If your budget needs 45 minutes a week and a spreadsheet with 12 tabs, you will stop using it. I did.
- They treat all spending as equal. Spending $500 on a course that raises your income is not the same as spending $500 on clothes. A good wealth building budget knows the difference.
The Federal Reserve's household survey data has repeatedly found that a large share of American adults could not cover a $400 emergency expense with cash. That is not a spending problem alone. That is a system problem. The system most people use does not put wealth first.
You need a different approach. That is where the reverse budget comes in.
The Reverse-Budget Framework
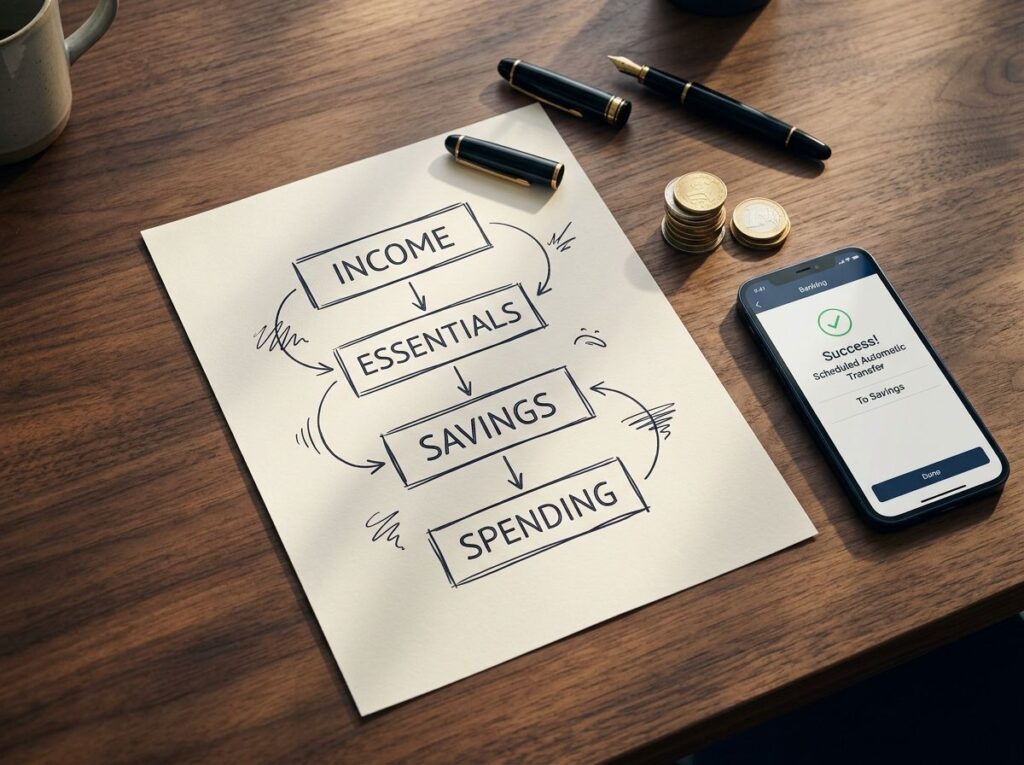
A normal budget asks, 'How much can I save after I pay my bills and live my life?' A reverse budget asks, 'How much do I need to save and invest to hit my goals, and then how do I live on the rest?'
It flips the order. Wealth comes first. Everything else comes after.
Here is how it works in four steps.
Step 1: Pick Your Wealth Number
Decide what percentage of your income goes to building wealth. This includes savings, investments, and debt payoff above the minimum. For most people, 20% is a good starting point. If you can do 30%, even better. If 10% is all you can manage right now, start there and raise it later.
Step 2: Automate It
The day you get paid, that percentage moves out of your checking account. It goes to your savings, your investment accounts, and your debt. You never see it. You cannot spend what you cannot see.
Step 3: Pay Your Fixed Bills
Rent, utilities, insurance, minimum debt payments. These are the same every month. Pay them next.
Step 4: Live on What Is Left
This is your spending money. It covers food, gas, fun, and everything else. When it is gone, it is gone. No guilt. No tracking every receipt. You already did the important part.
This is how budgeting for millionaires actually works. They do not track every coffee. They decide what to build, automate it, and live on the rest.
The reverse budget is simple. It is also the only budget I have been able to keep for more than a year.
Sample Allocations at $60K, $100K, and $200K
Your numbers depend on where you live and what you owe. But seeing real examples helps. Here is how I would set up a wealth building budget at three income levels.
At $60,000 Per Year
You bring home about $4,000 per month after taxes in most states. Your wealth number is 20%, or $800 per month. The rest, $3,200, covers rent, food, and life. This is tight but doable. I did it on less.
At $100,000 Per Year
You bring home about $6,200 per month after taxes. Your wealth number is 25%, or $1,550 per month. The rest, $4,650, covers your life. You probably have more room here for travel and fun.
At $200,000 Per Year
You bring home about $11,500 per month after taxes. Your wealth number is 35%, or about $4,000 per month. The rest, $7,500, covers a comfortable life. At this level, your biggest risk is lifestyle creep. Do not let your spending grow as fast as your income.
| Income | Take-Home / Month | Wealth Number | Monthly to Wealth | Left to Live On |
|---|---|---|---|---|
| $60,000 | $4,000 | 20% | $800 | $3,200 |
| $100,000 | $6,200 | 25% | $1,550 | $4,650 |
| $200,000 | $11,500 | 35% | $4,000 | $7,500 |
These are starting points, not rules. The right number is the one you will actually stick to.
One more thing. If you have side income, like a rental or a digital product, you can build passive income streams. That changes your budget.
Automating Your Wealth Budget
The best budget is the one you do not have to think about. Automation is the key. When your wealth-building happens without your input, you cannot forget it or talk yourself out of it. It is one of the most reliable millionaire habits there is.
Here is how I set mine up.
- Direct deposit split. I have part of my paycheck go straight to a savings account. It never hits my checking. Out of sight, out of mind.
- Automatic transfers. On the 1st and 15th of each month, money moves from checking to my investment accounts. It is scheduled. I do not touch it.
- Automatic bill pay. All my fixed bills are on autopay. This keeps me from missing a payment and paying late fees.
- Automatic debt payments. My minimum debt payments are on autopay. Any extra goes automatically too.
- Separate accounts. I keep my spending money in a different account from my bills. This makes it easy to see what is safe to spend.
Once this is set up, your budget runs itself. You check in once a month for 15 minutes. You adjust if your income changes. That is it.
I also review my wealth number every six months. When I got a raise, I raised my savings rate. When my expenses went up, I looked for places to cut so my wealth number stayed the same. The goal is to never go backward.
Common Budgeting Mistakes
I made almost every mistake on this list. Learn from mine so you do not waste years like I did.
- Waiting until the end of the month to save. There is never anything left. Save first, spend second.
- Keeping up with friends who earn more. If your friend makes $200K and you make $60K, you cannot live the same life. That is okay. Your time will come if you stay disciplined.
- Ignoring irregular expenses. Car repairs, holidays, and annual insurance bills do not show up every month. Divide them by 12 and save that amount monthly. I keep a separate irregular fund for this.
- Not raising your wealth number when income grows. A raise is the best time to increase your savings rate. If you get a 10% raise, send at least half of it to wealth building.
- Using credit cards to cover gaps. If your budget does not work, fix the budget. Do not borrow your way through the month. That is how you stay broke.
- Comparing your budget to someone else's. Your life is not their life. Run your own numbers.
The biggest mistake is giving up after one bad month. You will have bad months. I have had plenty. The point is not perfection. The point is direction. If you save and invest most months, you will build wealth over time.
Tools and Apps
You do not need fancy software to build wealth. But a few tools make it easier.
- For automation: Your bank's automatic transfer feature is enough. Set it and forget it. Most banks let you schedule transfers for free.
- For tracking: A simple spreadsheet works. I use a Google Sheet with four columns: income, wealth, bills, spending. That is it. If you want an app, Mint and YNAB are popular. I used YNAB for two years. It is good, but it takes work. The reverse budget needs less tracking, which is why I switched.
- For investing: A low-cost brokerage like Vanguard, Fidelity, or Schwab. You can open an account in 15 minutes. Set up automatic investments and you are done.
- For debt: A simple list of your debts with balances and interest rates. Pay the highest rate first. No app needed.
Do not spend weeks picking the perfect tool. Pick one and start. The tool matters less than the habit.
Frequently Asked Questions
What percentage of income should go to investments?
Most experts suggest 15% to 20% of your gross income. If you can do more, do more. If you are starting out and 10% is all you can manage, start there. The most important thing is to start and then raise the number over time.
Is budgeting necessary if I earn a high income?
Yes. High income without a plan leads to high spending. I have seen people making $300,000 per year with almost no savings. A wealth building budget makes sure your money goes to assets, not just a bigger lifestyle. It matters at every income level.
How is wealth-building budgeting different?
A normal budget focuses on tracking and cutting spending. A wealth-building budget puts savings and investing first. It flips the order. You decide your wealth number, automate it, pay your bills, and live on the rest. It is simpler and more effective for building long-term wealth.
Conclusion
Building wealth is not about being cheap. It is about being intentional. The reverse-budget framework puts your wealth first, automates it, and lets you live on the rest without guilt. It is the only budget I have been able to keep for the long run.
Start with a wealth number. Even 10% is a start. Automate it. Pay your bills. Live on what is left. Then raise your number when your income grows. That is how you budget for wealth building.
Start building your plan today. Run the numbers before you decide. Your future self will thank you.